
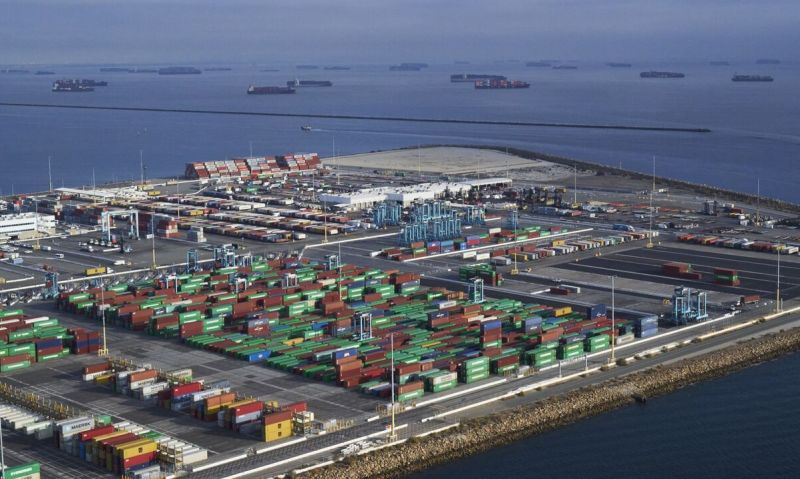
According to Linerlytica, a container shipping industry analyst conglomerate, increased port congestion has exacerbated the troubles of the overstretched container market.
Linerlytica noted that the global port congestion indicator hit the 2 million TEU mark, accounting for 6.8 per cent of the global fleet with Singapore becoming the new congestion hotspot.
Berthing delays at the world’s second-largest container port have reached up to seven days, with the total capacity waiting to dock increasing to 450,000 TEU in recent days.
The extreme congestion has led some carriers to cancel their planned Singapore port calls, exacerbating the difficulty in downstream ports that would have to manage increased loads.
The delays have also resulted in vessel bunching, which has caused spillover congestion and scheduling difficulties in downstream ports.
The increase in port congestion has pulled over 400,000 TEU of vessel capacity out of circulation in only the previous week, with the situation anticipated to worsen further in the following month.
Regarding freight rates, the Shanghai Container Freight Index (SCFI) has risen by 42 per cent in the last month, with more rises expected in June as carriers implement new fees and rate hikes.
Carriers have been obliged to obtain new boxes and vessel contracts beyond September due to their initial reluctance to commit too far ahead if demand drops after the summer peak season.
Carriers have maintained their cautious full-year prognosis, with ZIM being the last of the major carriers to announce first-quarter data last week.
However, according to Linerlytica, market signals are currently positive, reflecting the rate hikes that began in 2021 and continued until the end of 2022.
Recently, Sea-Intelligence reported that owing to widespread port congestion, shipping companies were forced to cancel sailings despite high demand and freight rates, resulting in a scarcity of available vessel capacity.