
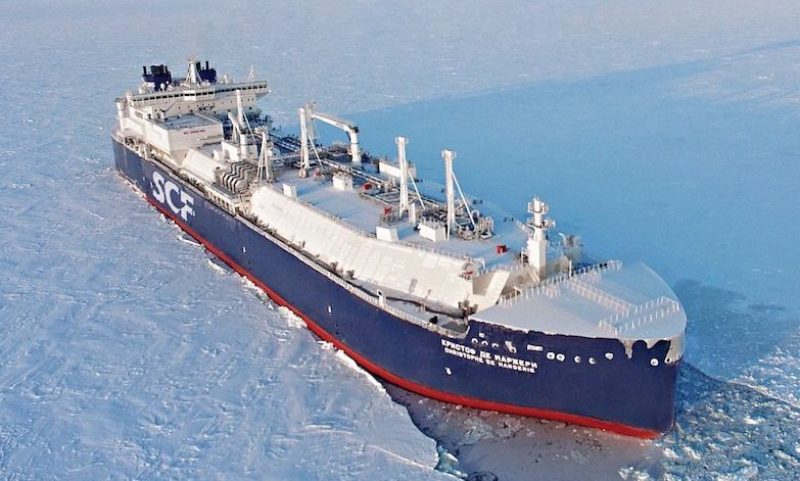
Russia’s crude oil shipments to Asia through the Arctic’s Northern Sea Route (NSR) have increased by nearly 50% year on year, reaching approximately 20 million barrels between the start of the navigation season in July and mid-October 2026. Disruptions to major global shipping corridors and soaring tanker freight rates are making the route increasingly attractive to Russian oil exporters.
The Northern Sea Route connects Russia’s western ports with Asian markets through Arctic waters, offering an alternative to conventional shipping routes through the Suez Canal and Red Sea. Although the passage involves challenging ice conditions, elevated safety risks and additional costs for icebreaker assistance, the current freight market has improved its relative attractiveness.
Shipping disruptions linked to conflicts in the Middle East and Ukraine have affected established trade corridors, including the Strait of Hormuz, the Suez Canal and the Black Sea. These developments have pushed tanker freight rates to exceptionally high levels, encouraging exporters to consider alternative routes for delivering crude oil to Asian buyers.
Russia shipped approximately 13 million barrels of oil through the Arctic route during the entire 2025 navigation season. The 2026 volume had already exceeded that total by mid-October. Traders estimate that another 5 million to 10 million barrels could move through the route before the navigation season ends, potentially bringing the total to 25–30 million barrels.
Russian energy companies are also planning to increase their use of the corridor. Gazprom Neft Chief Executive Alexander Dyukov has indicated that the company expects its Arctic-route shipments to rise by around 35% in 2026 compared with the previous year.
The expansion of the Vostok Oil project in northern Russia is expected to provide additional cargo for the route. The Northern Sea Route also handles liquefied natural gas (LNG) and other commodities, supporting Moscow’s wider ambitions to expand Arctic trade.
However, the route remains highly seasonal, with navigational conditions and the availability of suitable vessels limiting its operating window. The requirement for specialised ships and icebreaker support also means that its commercial viability depends heavily on freight rates, ice conditions and the cost of alternative routes.
For global shipping and energy markets, the increase highlights how geopolitical instability can reshape maritime trade flows. While the Arctic corridor offers Russia another option for reaching Asian customers, its long-term growth will depend on infrastructure, vessel availability, navigational safety and the economics of transporting oil through Arctic waters.